Greenlight Kids & Teen Banking
Greenlight Financial Technology, Inc.FinanceVerified
- 10.63K Reviews
- 4.7
- Downloads
- 1,000,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
When a child’s card is declined or a parent can’t find the right control, a money app can suddenly feel less like a teaching tool and more like another thing to troubleshoot. I find Greenlight Kids & Teen Banking most useful when a family treats it as a shared routine: the adult sets the boundaries, and the young person gets regular chances to make small decisions within them. That balance matters more than any colorful screen.
Greenlight is a finance app from Greenlight Financial Technology, Inc., built around a debit card for children and teens that parents manage from an app. It is free to install, rated for Everyone, and has a 4.7 average from around 80,000 ratings. Those figures suggest broad interest, but they don’t tell you whether its family-centered approach fits your household. I’d judge it by whether both parent and child are willing to check in and talk about spending, not by the rating alone.
Where families can get stuck
The most common friction with a parent-managed card is not necessarily the app itself; it is figuring out who needs to do what. A child may expect a card to work like any other payment card, while a parent expects to review activity or set rules first. Before relying on it for a time-sensitive purchase, I would make sure the adult and child understand how the family plans to handle spending decisions and what to do if a payment does not go through.
There is also a learning curve in deciding how much oversight is helpful. If every purchase becomes a debate, the card can feel like surveillance rather than practice. If the child has no clear boundaries, the parent may feel they are reacting after the fact. I’d start with a simple agreement: what the young person can decide independently, which purchases need a conversation, and when you will review the account together.
Greenlight is designed for families who want an adult involved, so it is not the best match for a teen who needs a fully independent banking arrangement. It may also be more structure than a family wants if a parent is happy to hand over cash and talk through purchases informally. The useful question is whether having a dedicated card and a shared app will make money conversations easier—or just add another account to manage.
What’s Inside the Greenlight Experience?
Alright, so let’s dig into what Greenlight Kids & Teen Banking has to offer. First off, the app is more than just a digital banking tool; it’s a complete financial education platform. The app allows parents to set up debit cards for their kids, which can be used for spending, saving, and even investing. Yes, investing! Imagine your 12-year-old getting a head start on the stock market—kind of cool, right?
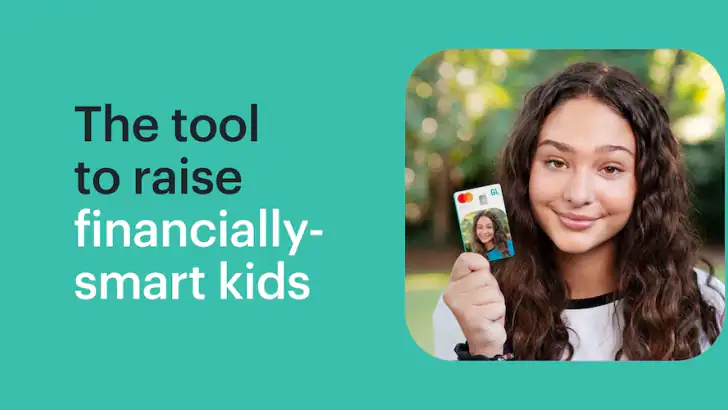
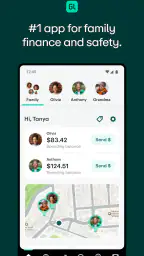
The interface is super user-friendly. Kids can easily check their balance, set savings goals, and track their spending. The learning curve isn’t steep, so even tech-challenged parents can get the hang of it. The app's visual layout is appealing, with bright colors and intuitive navigation, making it attractive for younger users.
Other Stories to Read




Setup checks that prevent avoidable hassle
Greenlight’s current version is 7.29.0, and it requires Android 10 or later. Before installing, I would check the phone’s operating system and confirm that the parent and child know which device and account they intend to use. A setup that begins with mismatched expectations—such as the child thinking they can manage everything alone—can create more confusion than the app’s menus do.
I’d also decide on the first real use case before setting up a routine. Is the card mainly for school-day purchases, a regular allowance, or saving toward something specific? A clear purpose helps a child understand what the balance means. It also gives the parent a sensible way to explain why some spending is fine while another purchase needs a check-in.
One practical tip is to make the first review low stakes. Rather than introducing the app during a rushed morning or right before an outing, sit down together when there is time to look at the balance and talk through what the child expects to buy. That gives both sides room to learn the flow without a declined transaction turning into an argument.
Parental Controls and Features
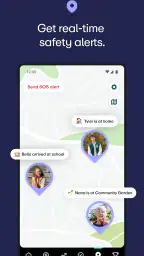
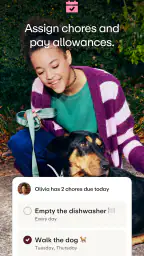
One of the standout features is the robust parental control options. Parents can manage the allowances, set up chores for extra cash, and even lock the card if it goes missing. There’s a real-time notification feature that alerts parents every time the card is used, so you’re always in the loop about where your kid is spending their money.
Plus, you can set spending limits on specific categories like entertainment or online shopping. It’s a great way to teach kids about budgeting without having to sit them down for a boring lecture.
These controls work best when they are part of a conversation, not a surprise. If a parent changes a limit, I’d explain the reason and let the child ask questions. That small habit makes a restriction feel like a budgeting rule rather than an arbitrary punishment. For older teens, agreeing in advance on what the parent will monitor can also help preserve trust while keeping the adult involved.
A realistic routine for spending and review
Picture a teen using the card for a snack after school and saving toward a larger purchase. The parent can use the activity as a prompt to ask whether the snack was planned and whether the savings goal still feels worthwhile. The point is not to audit every small choice; it is to help the teen notice how everyday spending affects a goal they care about.
A useful workflow is to check the balance before a planned outing, then look at activity together afterward. If the child is saving, agree on a reasonable amount to set aside before deciding what is available to spend. This makes the app’s balance and goals part of a concrete decision, rather than numbers the child checks only when they want to buy something.
For parents, notifications can be helpful but may also create noise if each transaction becomes an immediate conversation. I would use alerts as awareness, then choose a calm time for broader money discussions. That distinction keeps the app from turning routine purchases into constant supervision.
Saving and Investing: A Path to Financial Literacy
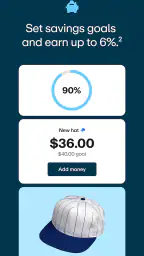
Beyond just spending, the app encourages saving through various means. Kids can create saving goals and track their progress. The app even offers a feature where parents can add interest to savings, simulating a real bank environment. It’s a fantastic way to show kids the benefits of saving over time.
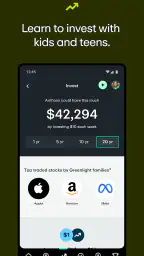
The investing feature is another unique aspect that caught my attention. It’s a simple way for kids to start learning about stocks with parental guidance. The app provides a breakdown of different stocks and their performance, making it easy for young users to understand the basics of investing.
For a younger child, I’d begin with a goal they can picture—a gift, a game, or another purchase they have chosen—rather than starting with abstract lessons about long-term returns. A parent-added interest amount can open a conversation about patience and growth, but it should be explained as a family learning exercise, not a promise about what savings will earn elsewhere.
Investing is a different kind of lesson from saving for a near-term purchase. It introduces uncertainty as well as the idea that investments can change in value. I’d approach that section with a teen who is ready to ask questions and discuss risk, and with a parent prepared to guide the conversation. If the family only wants a simple way to separate allowance from savings, the investing element may not be a reason to choose the app.
Recovering when a payment or card routine goes wrong
If a card is misplaced, the parent controls described in the app provide a sensible first place to respond: check the account and use the available card-lock option. For a payment that does not work, I would avoid repeatedly trying the same purchase before checking the basics. Confirm that the child is using the intended card, that the family has reviewed the account, and that the purchase fits the rules they agreed on.
It also helps to distinguish a card problem from a misunderstanding. A child may not know whether a purchase is allowed, or a parent may have expected to discuss it first. In that case, a quick conversation is more useful than changing several settings in a hurry. Once the family has identified what happened, they can decide whether the next step is a rule clarification or a technical check.
Security: Keeping It Safe
Of course, with any financial tool, security is paramount. Greenlight Kids & Teen Banking implements bank-level encryption and fraud detection to ensure safety. The app also has a feature to block certain stores or websites if necessary, giving parents peace of mind.
Additionally, if a card is lost or stolen, parents can instantly lock the account, preventing unauthorized transactions. This security-first approach is reassuring, especially when dealing with kids’ finances.
Security tools can reduce worry, but they do not replace basic family habits. I’d make sure a child knows to tell a parent promptly if the card goes missing and to avoid sharing account or card details casually. The parent should also be the person who handles account-level decisions, while the child learns how to report a concern. This division gives the young person a real role without placing adult responsibilities on them.
When the app may not be the cause
Not every confusing payment experience points to a software fault. The child may have misunderstood a family limit, the parent may be looking at a different part of the account, or the card may simply not be available when they expect it. I’d first compare what happened with the family’s agreed spending rules and the account information shown in the app.
If the app itself is behaving unexpectedly, a measured check is better than changing several things at once. Make sure the device meets the Android 10 minimum, close and reopen the app, and confirm that you are using the intended account. If the issue remains, use the app’s available support route rather than guessing at a workaround involving sensitive financial details.
Families using an iPhone should check the current app-store requirements on their device before relying on a particular setup. The Android requirement is clear, but device compatibility can differ by platform and can change over time. That is a practical check to make before planning a child’s first outing around the card.
How it compares with simpler alternatives
Compared with cash, Greenlight can make a child’s spending and saving more visible to both the child and parent, while cash can be easier for a young child to understand physically. Cash also avoids app setup, but it does not provide the same shared digital record or card controls described here. A family that wants hands-on practice counting money may prefer to keep cash in the mix.
Compared with a basic debit card, Greenlight’s appeal is the parent-managed structure and its emphasis on helping children build money habits. That structure is also the trade-off: adults need to participate, and the child is not simply opening an independent account. For a teen who mainly needs ordinary banking autonomy, a youth account offered through a bank may be a better fit; for a parent who wants guided practice, Greenlight is more purpose-built.
The app is free to install, but I would not confuse that with a guarantee that every service or plan is free. The published subscription details should be checked before a family commits to a paid arrangement. That matters especially if you are comparing it with cash or a simple card that has no ongoing family-app cost.
Who gets the most from it?
I think Greenlight is strongest for a family that wants to make money management a recurring, low-pressure conversation. It can suit a parent who is ready to oversee a child’s spending and a young person who is curious about handling their own purchases. It is less compelling if the adult does not want to manage a separate family finance app or if the child is not ready to work within shared rules.
The app has been available since December 23, 2016, and has passed one million installs. Its 11,000 reviews offer a larger body of user feedback than a newly launched app would, though individual experiences can still differ. I would treat its established presence as context, not a substitute for checking whether the current plan and setup meet your family’s needs.
Is It Worth It?
Now, let’s talk about the elephant in the room—cost. The app isn’t free, but considering the features and peace of mind it offers, it’s a worthwhile investment in your child’s financial education. There are different subscription tiers, each offering a variety of features. It’s best to weigh what each level includes to find what suits your family’s needs.
From my experience, the app seamlessly blends education with practicality. It’s not just about managing money but understanding it. Kids learn valuable financial skills that will undoubtedly help them in the future.
So, if you’re looking to instill good money habits in your kids and give them a financial head start, installing Greenlight Kids & Teen Banking might just be the way to go. It’s fun, educational, and most importantly, it empowers kids to take charge of their financial future. And who knows? Your kid might just become the next Warren Buffett!
My practical verdict is positive for families who will use the parent controls as a teaching aid rather than expecting the app to teach by itself. Start with one clear purpose, such as allowance or saving toward a chosen goal, and review how the routine feels before adding more complexity. If your priority is a child’s independent bank account, or you want to avoid ongoing app-based oversight, compare alternatives first. For parents and kids who are willing to learn together, Greenlight gives everyday spending a useful starting point for conversations that might otherwise never happen.
Highlights
- User-friendly interface for easy navigation.
- Parental controls ensure safe usage.
- Educational resources for financial literacy.
- Real-time transaction tracking for parents.
- No monthly maintenance fees.
Limitations
- Limited features for older teens.
- Requires stable internet connection.
- No international transaction support.
- Some features are app-exclusive
- not web.
- Customer support response time varies.
Frequently Asked Questions
01What is Greenlight Kids & Teen Banking?
Greenlight Kids & Teen Banking is a financial app designed to teach children and teenagers about money management. It offers features like chore tracking, allowance management, and savings goals, empowering young users to learn financial responsibility under parental supervision. The app also provides real-time notifications and spending controls.
02How secure is the Greenlight app for my child’s financial data?
Greenlight prioritizes security by implementing bank-level encryption to protect user data. It also provides parental controls to monitor transactions and spending. The app requires multi-factor authentication for account access, ensuring that both your child’s information and funds are safeguarded against unauthorized access.
03Can my child use Greenlight for online and in-store purchases?
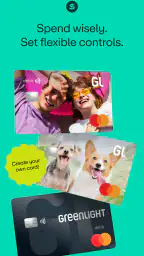
Yes, Greenlight provides a debit card that can be used for online and in-store purchases wherever Mastercard is accepted. Parents can set spending limits and approve or decline specific transactions, giving them oversight while allowing children to learn how to manage their own money responsibly.
04What parental controls are available in Greenlight?
Greenlight offers extensive parental controls, allowing parents to set spending limits, track transaction history, and receive real-time notifications. Parents can also allocate funds for specific purposes like savings or spending and approve or reject purchases. These features ensure parents have full visibility and control over their child's financial activities.
05Are there any fees associated with using Greenlight?
Greenlight operates on a monthly subscription model, which covers all features including the debit card and parental controls. While there may be a nominal fee, many users find it a small investment for the comprehensive financial education and security features offered. Be sure to check their website for the latest pricing details.


